

Global Market and Economic Perspective
Global Economic Commentary
- Second quarter real economic growth in the U.S. came in at 1.5% which was somewhat below expectations. Steady consumer spending alongside a surge in AI-related investment continues to underpin growth as contributions from government spending and international trade have waned. Across developed markets outside the U.S., growth has slipped below 1%. Despite slowing growth in China, aggregate emerging markets growth remained steady given particularly notable AI-related investment concentrated in other Asian markets.
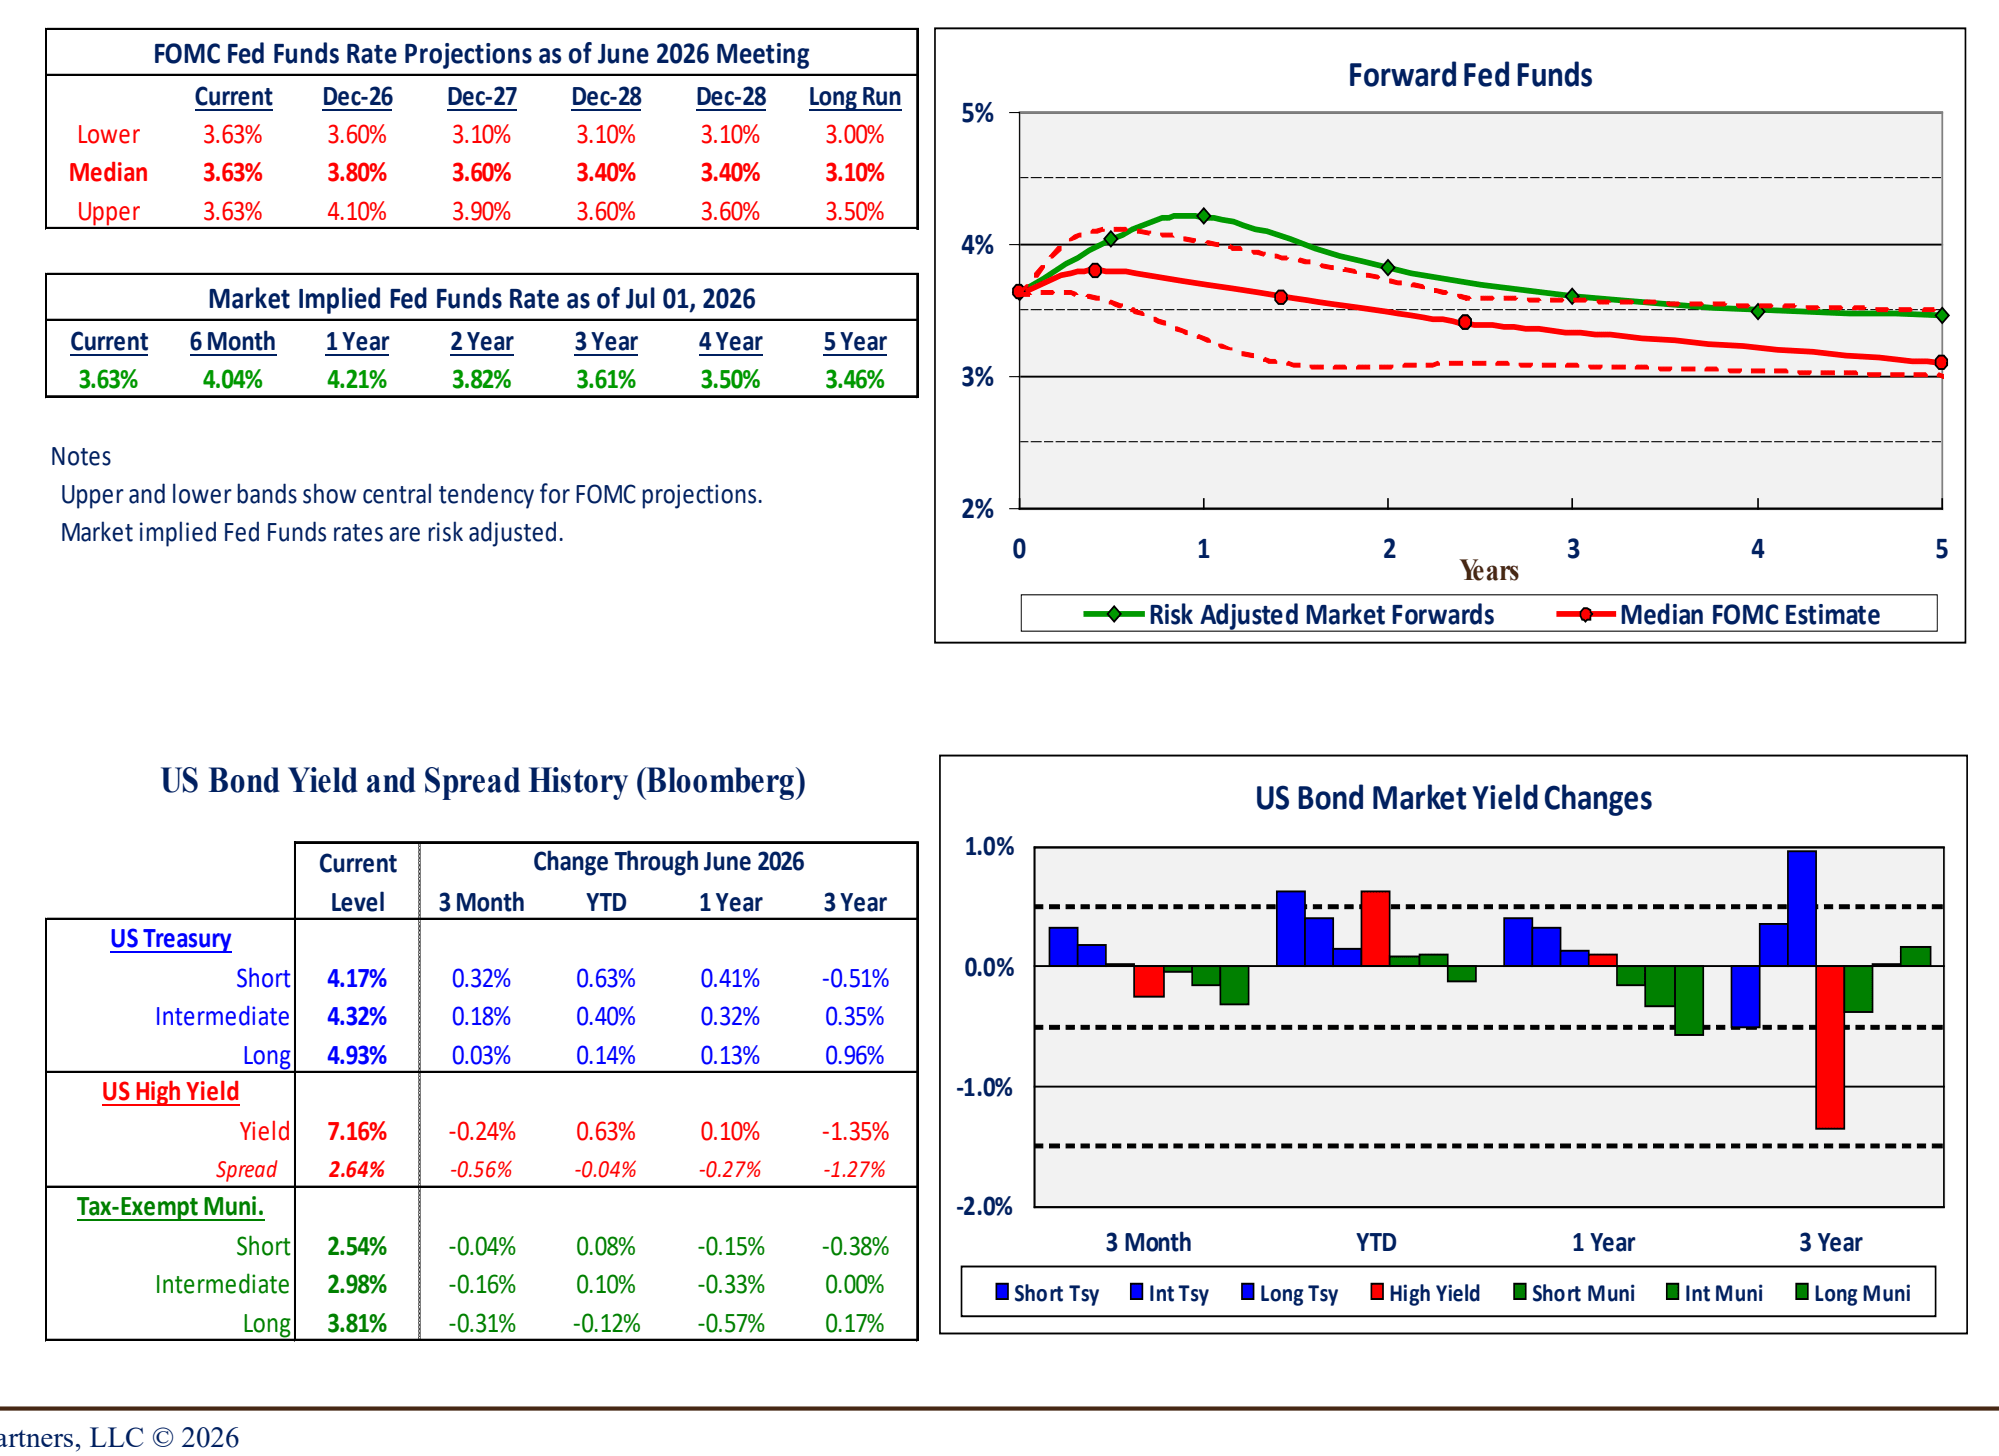
- Inflation remains above targets for most major developed markets. After guiding expectations toward a continuation of its (slow) hiking cycle, the Bank of Japan increased rates from 0.75% to 1.0% in June. The European Central Bank also opted for its first hike since 2023 (from 2.0% to 2.25%), while the Bank of England and the Fed left UK and U.S. policy rates unchanged for the quarter. The effective U.S. Federal Funds rate remains at 3.63%, where it has been since December of last year.
- Unemployment during the quarter remained just above recent lows in most developed countries, while continuing to slowly trend lower in emerging markets economies (and particularly across Latin America).

Stairway Partners is an SEC-registered Investment Advisor providing comprehensive investment advice and industry-leading portfolio management solutions. Our firm was created to provide institutions and individual investors with transparent and cost-effective stewardship of their assets. Our sophisticated investment capabilities and a steadfast commitment to the industry’s best practices have allowed us to serve as a valued advisor and trusted fiduciary to clients throughout the United States. For more information, please call (630) 371-2626 or email us at stairwaypartners@stairwaypartners.com.
Global Equity and Currency Commentary
- Global equity market performance was strongly positive in the second quarter. Within the U.S., growth stocks outperformed value stocks, while small cap stocks outperformed large cap stocks.
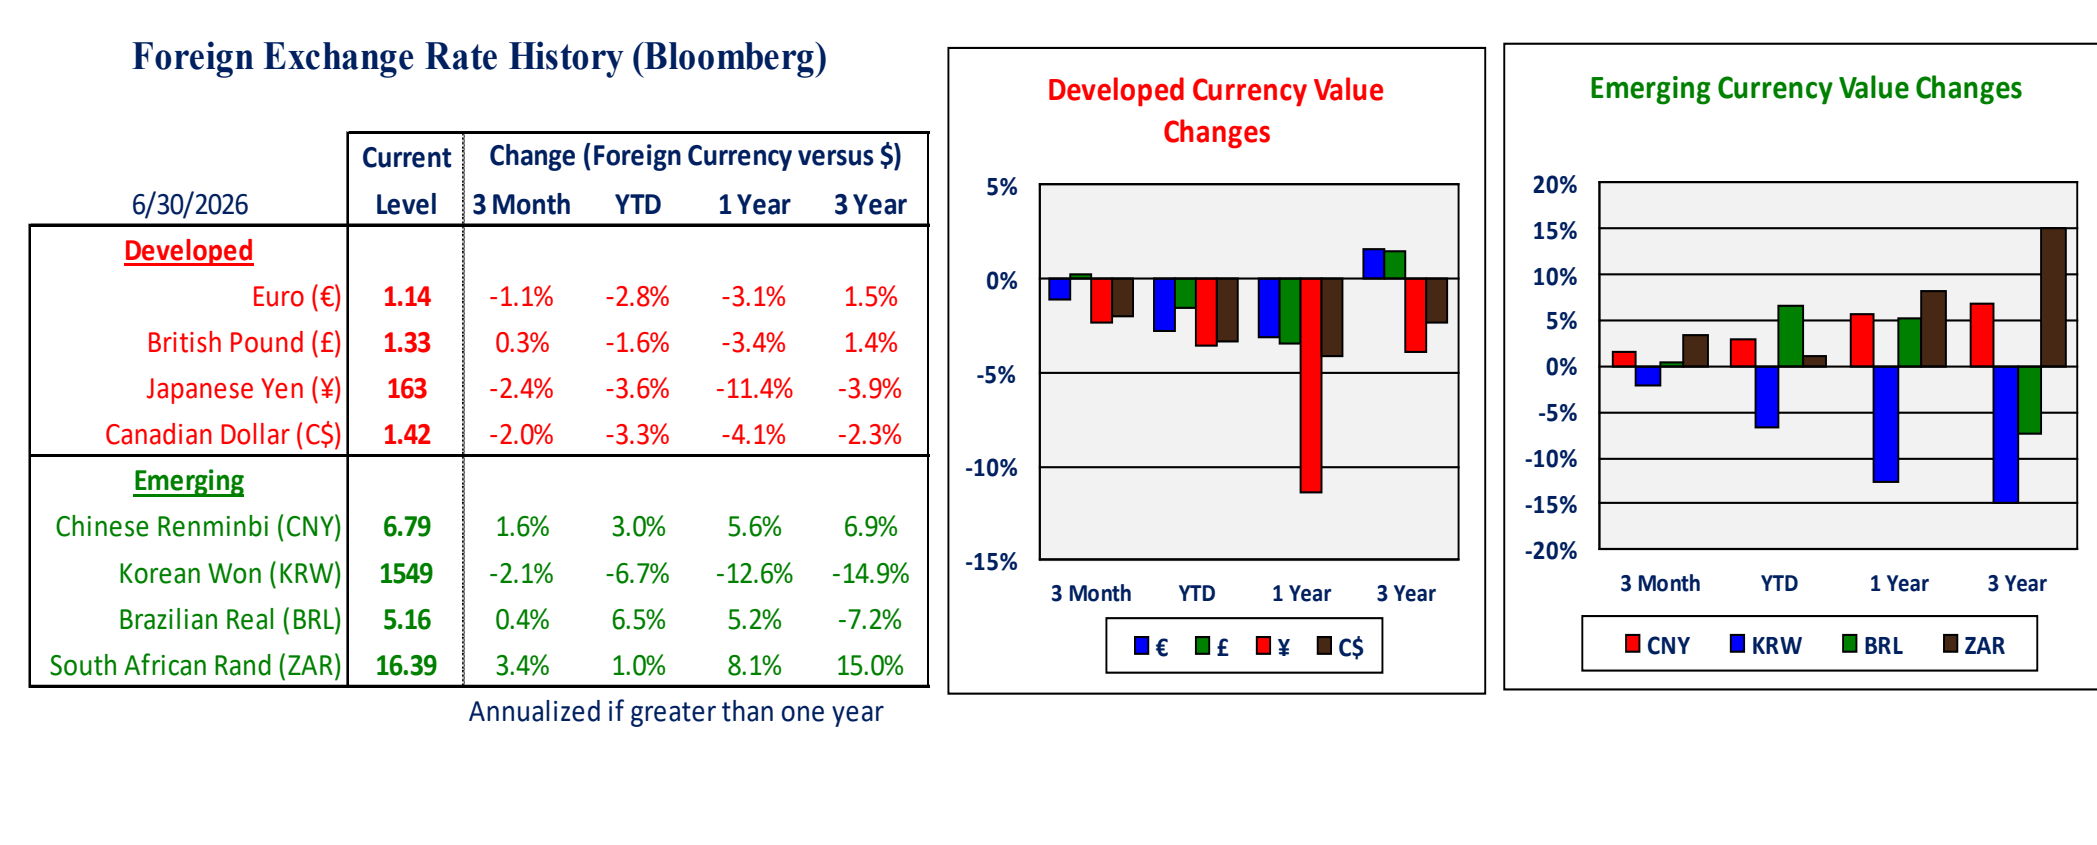
- Emerging markets equity outperformed developed markets through the first half of 2026 with particularly strong local market returns and a negligible impact from currency in the second quarter. More specifically, the bulk of the outperformance came from outstanding gains in semiconductor stocks in Asia.
- Non-U.S. developed market equity underperformed both U.S. and emerging markets equity during the quarter. Yet, these markets also delivered solid absolute local market performance with currency detracting slightly.

US Fixed Income and Fed Commentary
- In the second quarter, the upward-sloping Treasury yield curve flattened, as yields increased more for shorter-maturity than longer-maturity securities. The FOMC left rates unchanged during the quarter, as expected, while near-term projections began to indicate a modest, yet increased, likelihood of a hike before year end.
- Credit spreads tightened for the quarter in both investment grade and high yield debt markets. In combination, the increase in Treasury yields and decrease in credit spreads led to positive returns in both investment grade and high yield fixed income markets.
- Kevin Warsh began his term as Fed chair in May and stepped into an FOMC that has had a challenge finding consensus recently. The FOMC has continued to leave policy rates unchanged this year. While affirming the Fed’s mandate, the new chairman has established several task forces to evaluate longer- run questions around the core functions of monetary policy and the manner by which the Fed communicates with investors and the general public.
Stairway Partners, LLC © 2025
This material is based upon information that we believe to be reliable, but no representation is being made that it is accurate or complete, and it should not be relied upon as such. This material is based upon our assumptions, opinions and estimates as of the date the material was prepared. Changes to assumptions, opinions and estimates are subject to change without notice. Past performance is not indicative of future results, and no representation is being made that any returns indicated will be achieved. This material has been prepared for information purposes and does not constitute investment advice. This material does not take into account particular investment objectives or financial situations. Strategies and financial instruments described in this material may not be suitable for all investors. Readers should not act upon the information without seeking professional advice. This material is not a recommendation or an offer or solicitation for the purchase or sale of any security or other financial instrument.

You must be logged in to post a comment.